Barrick Mining has resolved its long-running Nevada Gold Mines dispute with Newmont, securing consent for its planned North American gold IPO and a $1.95 billion cash payment in the process.
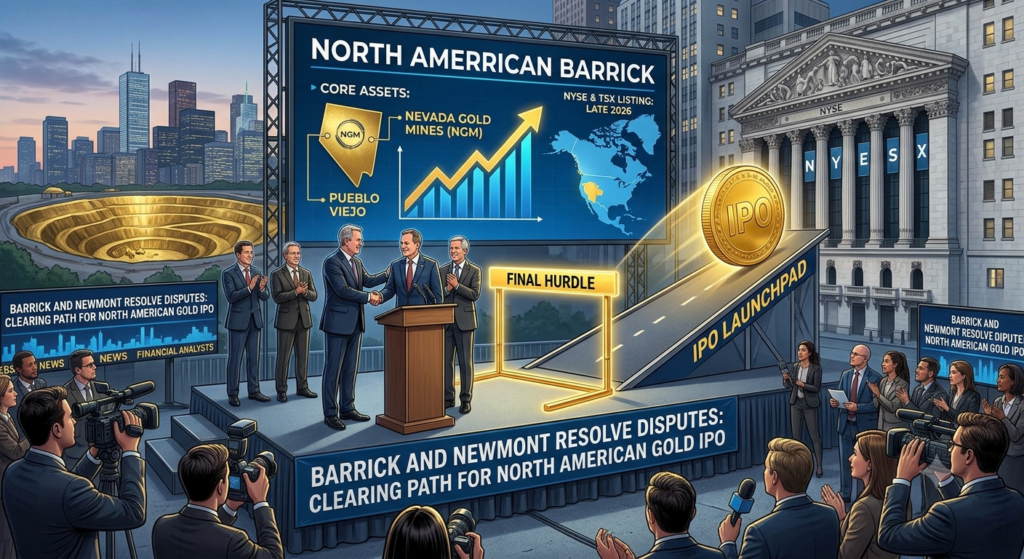
Barrick Mining Corporation has cleared one of the last major obstacles standing between it and a planned spinoff of its North American gold assets, announcing Monday that it has settled a lengthy dispute with joint venture partner Newmont Corporation over their shared Nevada Gold Mines operation — and secured Newmont’s formal blessing for the IPO in the process.
The Deal at a Glance
Under the newly amended agreement, both companies will contribute previously excluded properties into the Nevada Gold Mines (NGM) joint venture ahead of schedule. Barrick is vending in its Fourmile discovery, widely regarded as one of the most significant gold finds of the century, while Newmont is contributing its Mike and Fiberline developments. Combined, the move creates a Nevada gold complex holding close to 100 million ounces of gold — a genuinely massive resource base by industry standards.
As part of the settlement, Newmont will pay Barrick a $1.95 billion cash top-up payment within 30 days, compensating for the relative value of the assets being contributed by each side. Crucially, the agreement resolves every outstanding dispute between the two companies tied to the NGM joint venture, and includes Newmont’s formal consent to Barrick’s long-rumored plan to spin off its North American gold assets through an initial public offering.
Why This Dispute Mattered So Much
The friction between Barrick and Newmont wasn’t a minor disagreement. Since Barrick first floated the idea of an IPO for its top North American properties — including its Nevada assets and its stake in the Pueblo Viejo mine in the Dominican Republic — Newmont had pushed back hard, reportedly demanding a “rigorous operational overhaul” at Nevada Gold Mines before supporting any restructuring. That included calls for decentralized mine planning and a significant increase in automated operations to improve productivity.
The stakes were high because Newmont held real leverage: as a joint venture partner, it retained the right to potentially invoke a “Right of First Refusal” on the Nevada assets if Barrick’s planned IPO were deemed a change of control. That possibility gave Newmont significant negotiating power and created real uncertainty over whether Barrick’s IPO plans could move forward smoothly, or whether they might end up tied up in a prolonged legal fight instead.
Strong Underlying Results
The settlement arrived alongside Barrick’s second-quarter 2026 earnings, which showed a company performing well operationally even amid the ongoing corporate maneuvering. Gold production rose 11% sequentially to 796,000 ounces, beating internal guidance, while revenue grew 44% year-over-year to $5.29 billion.
Net earnings came in at $1.22 billion, or $0.73 per share, with adjusted earnings per share of $0.82, up 74% from the prior year. Operating cash flow increased 28% to $1.70 billion. Barrick also declared a quarterly dividend of $0.175 per share and repurchased $1.209 billion worth of shares during the quarter, pushing total shareholder returns for the period to $1.50 billion — a 242% increase compared to the prior year.
The company kept its full-year production and cost guidance unchanged, though it trimmed its total attributable capital expenditure guidance slightly, to a range of $3.8 billion to $4.2 billion.
What This Means for Barrick’s IPO Plans
With the Newmont dispute now resolved, Barrick’s path toward spinning off its premier North American gold assets — often referred to informally as “NewCo” — looks significantly clearer. The proposed structure would center on three cornerstone assets: Barrick’s majority 61.5% stake in Nevada Gold Mines, its 60% stake in the Pueblo Viejo mine, and its wholly owned Fourmile project.
The strategic logic behind the split is straightforward: Barrick wants to offer investors a clear choice between two distinct investment profiles. A newly spun-off entity would function as a high-yield, comparatively lower-risk pure gold producer, while the remaining parent company would pivot toward a growth-oriented, dual-commodity miner increasingly focused on copper. Barrick has already signaled that copper could account for 30% to 40% of the group’s earnings by 2030, reflecting a broader industry shift toward metals tied to electrification and renewable infrastructure.
A Long Road to This Point
This settlement caps off years of complicated history between the two mining giants. Barrick made a hostile takeover bid for Newmont roughly six years ago, which ultimately fell through, leading the two companies to instead form the Nevada Gold Mines joint venture as something of a truce in 2019. Since then, Barrick’s overall valuation has lagged behind some of its industry peers, a dynamic that analysts have pointed to as part of the motivation behind pursuing a standalone IPO for its most valuable assets.
With Newmont’s consent now secured and the underlying operational disputes settled, Barrick’s leadership — led by board chair John Thornton — appears positioned to move forward with the IPO from a position of considerably more strength and certainty than just a few months ago.
Frequently Asked Questions
Q: What did Barrick and Newmont agree to? The companies resolved all outstanding disputes tied to their Nevada Gold Mines joint venture, agreed to contribute previously excluded properties into the venture, and Newmont formally consented to Barrick’s planned IPO of its North American gold assets.
Q: How much will Newmont pay Barrick as part of this deal? Newmont will pay Barrick a $1.95 billion cash top-up payment within 30 days of the agreement.
Q: What assets is Barrick planning to include in its IPO? The planned spinoff centers on Barrick’s 61.5% stake in Nevada Gold Mines, its 60% stake in the Pueblo Viejo mine in the Dominican Republic, and its wholly owned Fourmile gold discovery.
Q: Why was Newmont’s consent so important for the IPO? As a joint venture partner in Nevada Gold Mines, Newmont held a potential Right of First Refusal that could have been triggered if Barrick’s IPO were considered a change of control, creating real legal and structural risk for the deal without Newmont’s agreement.
Q: How did Barrick perform financially in the most recent quarter? Barrick reported an 11% sequential increase in gold production, 44% year-over-year revenue growth to $5.29 billion, and adjusted earnings per share growth of 74%, marking its third consecutive quarter of strong operational and financial results.