Marvell Technology shares held a roughly 7.8% loss early Friday even after the chipmaker raised its revenue outlook, as analyst price targets diverged wildly following its second-quarter earnings report.
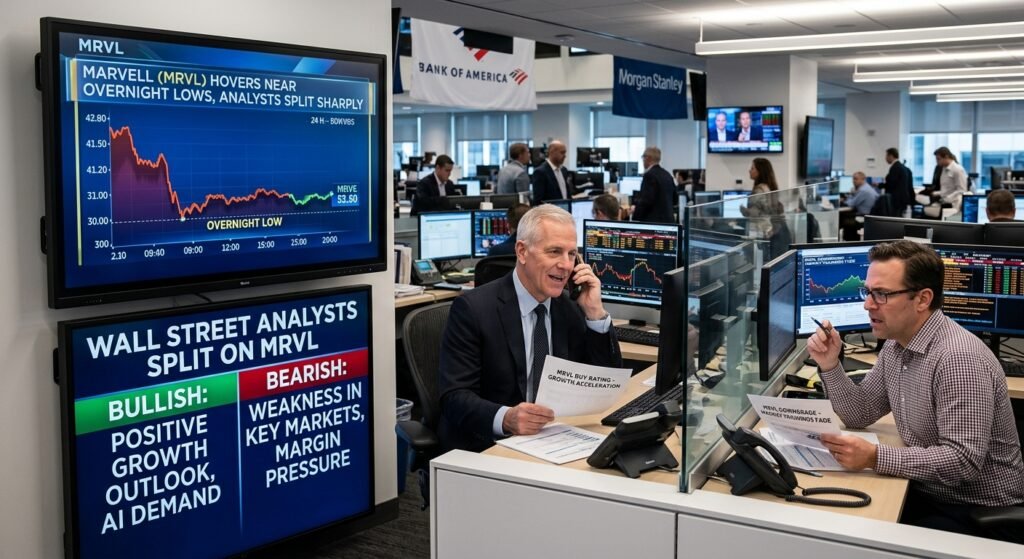
Marvell Technology’s stock spent early Friday trading pinned near its overnight lows, holding a loss of roughly 7.8% even after the chipmaker delivered raised revenue guidance alongside its latest earnings report — a disconnect that’s left Wall Street analysts sharply divided on what comes next for the stock.
A Confusing Reaction to Otherwise Solid Numbers
Marvell’s second-quarter results, released this week, actually included some genuinely encouraging signals. The company raised its revenue targets, continuing a pattern of strong underlying demand tied to its data center and AI-related chip business. Yet despite that improved guidance, shares failed to recover from an initial post-earnings slide, remaining stuck near a 7.8% loss into early Friday trading.
That kind of reaction, where a company beats or raises guidance but its stock still falls, typically signals that investors were pricing in even more optimistic expectations heading into the report, or that some other detail in the results (like margins, cost pressures, or forward commentary) gave the market pause despite the headline revenue news looking positive.
Why Analysts Can’t Agree on Marvell’s Fair Value
What’s made this stretch particularly notable is just how far apart Wall Street’s price targets on Marvell have become. Some analysts have grown considerably more bullish following the company’s recent performance, pointing to Marvell’s expanding position in custom AI chips and data center infrastructure as justification for higher long-term valuations. At the same time, other analysts have taken a far more conservative stance, citing concerns around near-term profitability, margin pressure, and increased competition in the market for AI-related semiconductor products.
This kind of wide analyst divergence isn’t unusual for a stock experiencing rapid, AI-driven growth expectations layered on top of genuine near-term earnings volatility, but it does leave everyday investors with a genuinely mixed signal to interpret, rather than a clear consensus view on where the stock is realistically headed from here.
Marvell’s Bigger Story This Year
Marvell has been one of the more closely watched names in the semiconductor space throughout 2026, largely due to its growing role supplying custom chips for AI data centers, a business that’s driven a significant share of investor enthusiasm around the stock over the past year. The company has previously highlighted that its AI-related revenue has significantly exceeded earlier internal targets, with management pointing to continued strength in demand from major data center customers as a key growth driver heading into the back half of the year.
That said, Marvell’s stock has also shown real volatility this year, reflecting the broader pattern seen across AI-adjacent chip stocks: strong underlying demand fundamentals paired with a market that’s grown increasingly sensitive to any signs that near-term spending or margins might not keep pace with elevated expectations.
The Broader Chip Sector Picture This Week
Marvell’s rocky reaction wasn’t happening in isolation. This week has been an eventful one across the semiconductor space more broadly. Intel shares climbed roughly 4.4% after Nvidia’s own forecast helped revive broader confidence in AI-chip demand, while other tech names posted notably strong post-earnings reactions of their own, including CrowdStrike, which surged more than 20% after its annual recurring revenue climbed to $5.84 billion.
That contrast, Intel and CrowdStrike rallying sharply on good news, versus Marvell struggling to hold gains despite raised guidance, underscores just how selective and reaction-specific this earnings season has become. Strong headline numbers alone aren’t guaranteeing positive stock reactions right now; investors appear to be scrutinizing the finer details of each report far more closely than the topline figures alone.
What This Means for Investors Watching Marvell
For anyone tracking Marvell specifically, the current setup is genuinely a “wait and see” situation. With analyst price targets ranging widely and the stock struggling to hold ground even after ostensibly positive guidance, the coming sessions are likely to hinge on how the broader market digests the full details of Marvell’s earnings call, along with whether upcoming commentary from company leadership can help narrow the current gap between bullish and cautious analyst perspectives.
Frequently Asked Questions
Q: Why did Marvell’s stock fall despite raising its revenue guidance? Even with improved revenue targets, Marvell’s stock remained down roughly 7.8%, suggesting investors may have been pricing in even higher expectations heading into the report, or reacted to other details in the earnings release beyond the topline revenue figures.
Q: Why are analyst price targets for Marvell so divided right now? Analysts are split between bullish views citing Marvell’s growing AI and data center chip business, and more cautious perspectives focused on near-term profitability, margin pressure, and rising competition in the custom AI chip market.
Q: How does Marvell’s earnings reaction compare to other chip stocks this week? It stands in contrast to names like Intel, which rose 4.4% on renewed AI-chip demand optimism, and CrowdStrike, which surged over 20% following strong recurring revenue growth, highlighting how selective investor reactions have become this earnings season.
Q: What is driving Marvell’s long-term growth story? Marvell’s growth has been closely tied to its expanding role supplying custom chips for AI data centers, with the company previously stating that its AI-related revenue has significantly exceeded earlier internal targets.
Q: Should investors be concerned about Marvell’s stock volatility? This isn’t financial advice, but the wide divergence in analyst price targets reflects genuine uncertainty in how the market is valuing AI-related chip demand right now, making it worth watching closely rather than assuming either the bullish or cautious view will clearly prove correct in the near term.